

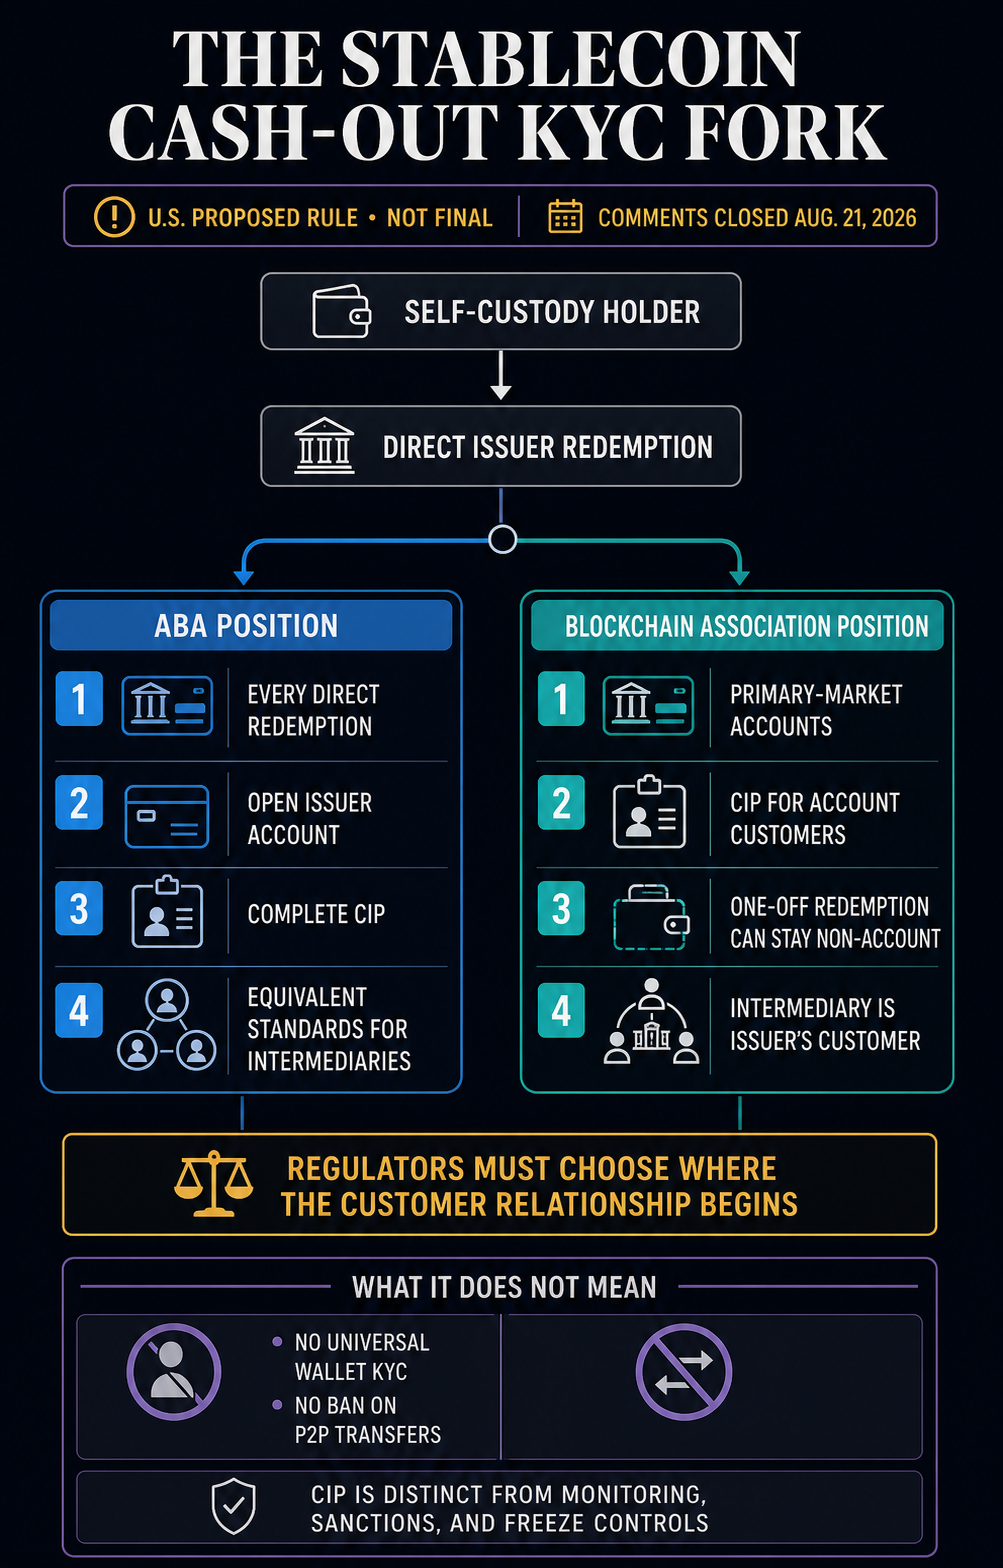
The American Bankers Association is pressing US regulators to require anyone who buys or redeems a payment stablecoin directly with its issuer to open an account and complete customer identification.
For a holder coming from self-custody, that would turn a direct cash-out into an issuer-onboarding event.
The Blockchain Association accepts identity checks for direct primary-market account customers but says an optional one-off redemption or a redemption routed through another regulated intermediary should not automatically make the underlying holder an issuer customer.
The disagreement surfaced in comments on a joint federal proposal for stablecoin issuer customer identification programs, known as CIPs.
The Federal Reserve’s public index lists the ABA comment as posted that day and the Blockchain Association comment as posted Aug. 24, alongside other R-1885 responses.
The agencies’ eventual choice will determine whether asking an issuer for dollars always opens an account or whether some holders can redeem without establishing that relationship.
The proposal leaves the cash-out boundary unresolved
The June proposal would require permitted payment stablecoin issuers to operate a CIP for customers who open accounts. A CIP is the account-opening process used to collect and verify a customer’s identifying information.
Directly issuing or redeeming payment stablecoins are among the activities the proposal says can establish an account. Token ownership alone is not enough, and a third-party transaction that interacts only with an issuer’s smart contract would not automatically make every user an issuer customer.
A self-custody holder can acquire stablecoins through an exchange, a payment, or a peer-to-peer transfer without dealing with the issuer. The next step can take two forms: the holder can seek dollars directly from the issuer, or an exchange or other intermediary can aggregate tokens and redeem on its customers’ behalf.
The agencies expressly ask whether a direct redemption by a holder with no prior issuer relationship creates an account. They do not answer that question in the proposal, leaving commenters to argue over who should complete the issuer’s CIP and when.
The ABA’s Aug. 21 letter recommends that anyone buying or redeeming a payment stablecoin directly with its issuer first open an account and be subject to the issuer’s CIP.
Under that approach, a holder could not make a one-off direct redemption as an unidentified non-customer. The issuer would collect and verify the information needed to establish an account before returning dollars.
The ABA also argued that exchanges and other secondary-market service providers should face equivalent customer-identification regulation and examination. It framed the recommendation as a way to maintain comparable standards across stablecoin and conventional financial channels.
The Blockchain Association agrees that direct primary-market account customers should undergo issuer CIP. Its comment asks regulators to preserve an issuer’s option to conduct a one-off redemption for a non-account holder without turning that transaction into account opening.
It also says that when another regulated intermediary presents stablecoins for redemption, that intermediary should be the issuer’s customer. The exchange or service provider’s downstream users should not automatically become customers of the issuer.
| Position | Identity trigger | Practical result |
|---|---|---|
| ABA | Every direct issuer purchase or redemption | The holder opens an issuer account and completes CIP before cashing out |
| Blockchain Association | A direct primary-market account relationship | An issuer can offer a one-off non-account redemption without automatically opening an account |
| Intermediary-routed redemption | Disputed | ABA seeks equivalent standards across channels; Blockchain Association treats the intermediary, rather than each underlying user, as the issuer’s customer |
Both positions concern direct issuer service and regulated redemption channels.
Circle and Paxos already gate eligible US stablecoin redemptions
Direct issuer redemption is already account-based and identity-checked for eligible US customers under terms published by Circle and Paxos. Their policies illustrate existing controls but do not establish a universal industry practice or settle what federal law should require.
Circle’s USDC terms route eligible direct US redemption through a Circle Mint account in good standing. Access to Circle Mint is limited to eligible users in supported jurisdictions and is governed by its user agreement, which requires account verification.
Paxos’ stablecoin terms likewise make direct redemption available to fully verified, eligible account customers, subject to the company’s stated controls.
A final rule that followed the ABA’s approach could make account-opening CIP the federal floor whenever a permitted issuer offers direct redemption, rather than leaving room for another structure.
Circle’s European policy shows that controlled redemption can take a different form. Under its MiCA redemption policy, eligible retail holders in the European Economic Area can use a dedicated form instead of the Circle Mint account product.
Circle still requires identity checks, transaction screening, freeze checks, and an eligible EEA bank account. The policy is a jurisdiction-specific contrast, not a description of the proposed US regime.
A separate April federal proposal addresses broader anti-money laundering and sanctions programs, including transaction monitoring and reporting, sanctions screening, and duties or powers to block, freeze, or reject activity.
Those controls may apply to transactions or wallet activity without defining every token holder as an issuer account customer. In the other direction, completing CIP at redemption establishes the account customer’s identity.
The June proposal does seek comment on whether CIP obligations should extend further into secondary-market activity, so future expansion has not been ruled out.
For now, regulators are focused on the redemption boundary. The ABA would place the identity burden at the issuer every time a holder deals with it directly, while the Blockchain Association would keep issuer CIP tied to primary-market accounts and allow one-off or intermediary-routed cash-outs without automatically onboarding every underlying holder.
Until the agencies issue a final rule, both remain advocacy positions rather than binding law.
 Bitcoin
 Ethereum
 Tether
 BNB
 XRP
